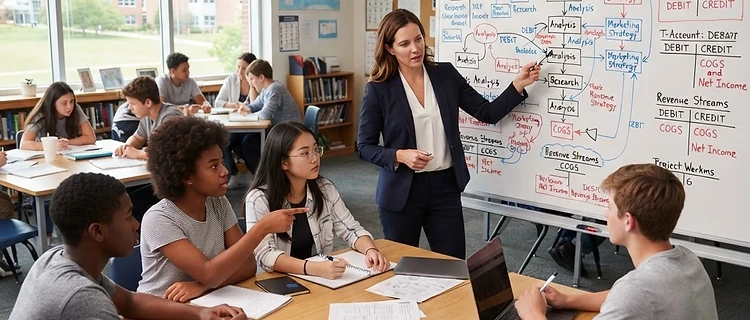
The Challenge of Rote Learning in Accounting
For many students the conceptual jump from basic arithmetic to the logical structure of double-entry bookkeeping feels like learning a secret code without a decoder ring. Relying on rote memorization such as repeating debit the receiver and credit the giver often leads to mechanical errors when students face complex Paper 2 scenarios. In this section we identify why students stumble when they lack a visual mental model of account flow. Pause and reflect for a moment on your last class session. Did your students struggle with the debits and credits because they lacked the technical knowledge or because they failed to visualize how the ledger balances represent a cohesive financial story? By moving away from rote rules and toward visual logic you transform accounting from a series of arbitrary commands into a structured system of cause and effect that even your lowest-attaining students can navigate with confidence.
Designing Visual Flowcharts for Double-Entry
A robust visual flowchart serves as an external brain for the learner during complex ledger adjustments. Instead of presenting a static list of rules create a decision tree that asks students to categorize the transaction type before determining the account effect. Try this in your classroom today by sketching a flow diagram on the whiteboard that requires students to answer three questions for every transaction. First is it an asset liability expense or income? Second does the account increase or decrease? Third what is the final debit or credit destination? By forcing this standardized diagnostic process you reduce the cognitive load significantly. As you develop your differentiated lesson plan for your portfolio consider how you might modify this flowchart for students with different processing speeds. Perhaps you use color-coding to denote increases and decreases visually, effectively bridging the gap between abstract accounting theory and the concrete reality of ledger mechanics.
Active Learning Strategies for Ledger Mechanics
Replacing passive note-taking with active learning strategies is essential for fostering deep understanding in the Cambridge IGCSE Accounting curriculum. One highly effective strategy is the use of human T-accounts where students physically move to represent the movement of funds between ledgers. Another approach involves collaborative peer-correction tasks where students exchange ledger scripts and must identify discrepancies in balancing. Consider the efficacy of digital simulation tools that allow students to manipulate T-account entries in real time. These methods move the student from being a passive recipient of information to an active auditor of their own learning. When you integrate these activities into your lesson plan ensure you document how you use them to scaffold learning for diverse learners. Ask yourself if these activities promote metacognition by forcing students to articulate why a debit or credit is necessary in any given context.
Scaffolding for Diverse Learning Profiles
Differentiation is not merely providing easier work but rather providing varied pathways to reach the same high-level accounting standard required by CAIE. Within your lesson plan you should incorporate tiered support such as partially filled T-accounts for learners who struggle with spatial organization or extension tasks that require high-achieving students to explain the impact of an error on the trial balance. Think about the student who consistently misplaces a debit. By using an overlay template or a guided prompt card you can provide the immediate feedback loop necessary to correct their thinking before it becomes an entrenched habit. Your portfolio capstone depends on your ability to prove that you can support these diverse learners while maintaining the rigors of 0452 standards. Reflect on how a visual aid like a traffic light system could help students signal their level of comprehension during complex balance sheet adjustments.
From Visual Logic to Assessment Success
Ultimately the goal of visualizing bookkeeping is to improve performance on Paper 2 structured ledger problems. Teachers must ensure that these visual tools are eventually phased out to prepare students for the examination hall conditions. As you refine your pedagogical approach consider how to transition your students from relying on complex flowcharts to using mental checklists that they have internalized. Use mock examination questions as the final test of your visual strategies, evaluating whether students can now map a wordy transaction to an accurate ledger entry without external support. Your portfolio readiness review will hinge on your ability to explain how these visual scaffolds directly contribute to higher marks in ledger adjustments. Keep detailed notes on how specific students progressed from visual reliance to independent accuracy. This data provides the concrete evidence needed for your professional self-evaluation and ensures your teaching remains grounded in actionable assessment outcomes.